Farmout Agreement Lawyer: Structuring Development Rights, Drilling Obligations, and Working Interests in Oil & Gas
A farmout agreement is one of the most consequential contracts an energy company will negotiate. It determines who drills, who pays, who earns acreage, and who bears the risk when a prospect either delivers or disappoints. Getting the structure right requires more than a template-it demands a farmout agreement lawyer who understands the upstream business, the regulatory landscape, and the financial architecture behind every well.
This page explains how farmout agreements work, what terms matter most, and how INK™ Law helps operators, investors, and working interest owners across Colorado, Texas, Wyoming, North Dakota, Oklahoma, Utah, Arizona, and beyond structure these transactions with precision.
Key Takeaways
- A farmout agreement is a contract in the oil and gas industry where the working interest owner (farmor) assigns all or part of its interest to another party (farmee) in exchange for the farmee performing drilling, testing, or development obligations-not for upfront cash.
- The farmor and farmee each have distinct objectives: the farmor seeks to preserve leasehold and limit capital exposure while retaining upside through an overriding royalty interest or back-in rights; the farmee seeks to acquire acreage and operatorship without paying full leasing costs.
- Farmout agreements share risk in high-cost drilling projects where drilling costs can reach tens of millions of dollars, making them a crucial tool for allocating capital, geological risk, and operational control.
- These agreements are highly customized-not standardized forms-so careful legal drafting and alignment with joint operating agreements, oil and gas leases, and financing arrangements is essential. The lawyer plays a critical role in protecting the client’s interests in farmout agreements.
- INK™ Law is headquartered in Denver, Colorado and represents energy companies throughout the United States. Call (720) 307-2627 or message us online to discuss a farmout agreement review or new transaction.
What Is a Farmout Agreement in the Oil & Gas Industry?
A farmout agreement is a contract where a working interest owner-the farmor-agrees to assign all or part of that interest to another party-the farmee-if the farmee satisfies specified drilling, testing, or development obligations. A farmout agreement involves a farmor and a farmee, and the farmee must drill wells as a condition of the agreement.
Farmout agreements are common in the oil and gas industry because they allow the original leaseholder to move prospects forward even when capital, risk appetite, or operational capacity is limited. The farmor can continue operations without shouldering the full financial burden, while the farmee may bring the drilling equipment needed to advance the prospect and the farmor can retain an economic interest such as an overriding royalty interest, a carried interest, or back-in rights after payout. Farmees gain access to acreage without incurring full leasing costs or acquiring leases outright.
What distinguishes a farmout from a simple sale is that the transfer is contingent. The farmee “earns” the interest only after meeting defined milestones-such as drilling to a target formation, completing the well, or achieving production in paying quantities. Under 11 U.S.C. § 101(21A), a farmout agreement is defined as a written agreement where the owner of rights to hydrocarbons transfers part or all of such rights to another party that agrees to perform drilling, reworking, recompleting, testing, or related operations.
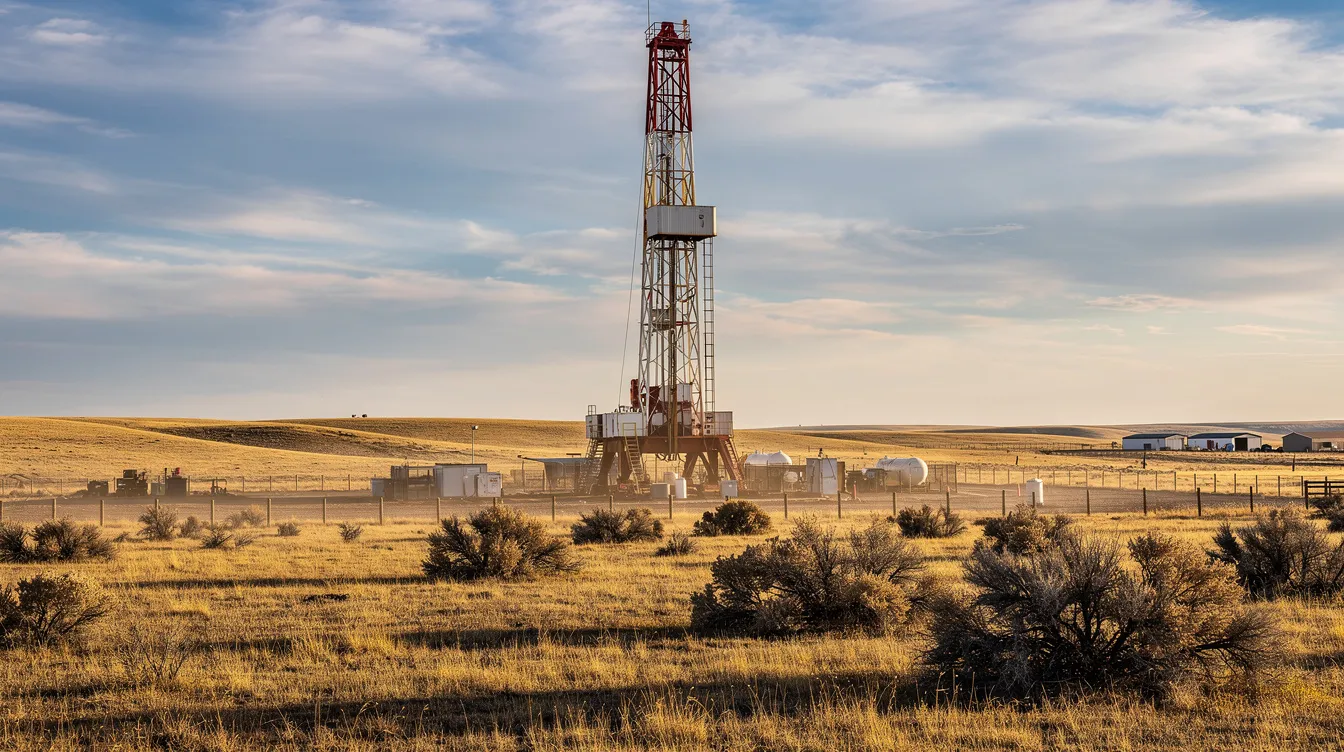
Consider a 2025 Niobrara shale prospect in Weld County, Colorado. The farmor holds leases approaching the end of their primary term but lacks the budget to spud a horizontal well. Under a farmout, a well-capitalized farmee drills the well, earns a working interest in the spacing unit, and the farmor retains an overriding royalty plus a back-in option after payout. In a multi-well Permian Basin farmout in Texas, the same concept scales across dozens of sections, with development schedules, depth limitations, and continuous drilling obligations layered in. Drilling costs in these plays can reach tens of millions of dollars per well, making farmouts an indispensable risk-sharing tool.
INK™ Law frequently works with operators, non-operators, and investors to determine whether a farmout, farm in, joint venture, or outright acquisition is the right structure for their development strategy. Reach out to our strategic energy law team for a confidential evaluation.
Roles of Farmor and Farmee: Working Interests, Risk, and Control
The farmor is the existing working interest owner looking to farm out acreage. The farmee is the party farming in, willing to invest capital and perform operations to earn an interest. Each side’s objectives directly shape the transaction.
Typical farmor goals:
- Preserving leasehold and avoiding lease expirations
- Satisfying drilling or continuous development obligations under existing oil and gas lease terms
- Limiting capital exposure and sharing risk
- Retaining upside through royalties, overriding royalty interests, or back-in after payout
- Obtaining geological information from the farmee’s operations
Typical farmee goals:
- Acquiring acreage and development rights without a large upfront cash purchase
- Securing operatorship and control over drilling schedules, well design, and AFEs
- Expanding an acreage position into new plays or basins
- Testing geological targets with favorable drill-to-earn economics
| Factor | Farmor | Farmee |
|---|---|---|
| Capital commitment | Limited; may be carried | Funds drilling and completion |
| Exploration risk | Shifted to farmee | Bears technical and commodity risk |
| Operational control | May retain approval rights or remain operator | Typically earns operatorship |
| Economic upside | Retained via ORRI, back-in, or carried interest | Earns working interest and net revenue |
Farmors can continue operations without full financial burden. Farmees gain access to acreage without leasing operations costs. Farmout agreements share risk in high-cost drilling projects, making them attractive to both sides when interests motivating each party align properly.
INK™ Law helps clients on both sides of the deal evaluate their leverage, negotiate commercial terms, and align the farmout with the client’s broader portfolio strategy and corporate governance. Call (720) 307-2627 to discuss your position.
Farmout vs. Farm-In: Two Sides of the Same Transaction
“Farmout” and “farm in” describe the same transaction from different perspectives. The farmor farms out; the farmee farms in. A farm-in agreement is typically the farmee’s perspective document for acquiring an interest in an existing gas lease or prospect area by performing work or funding operations rather than paying all cash.
Energy companies and investors in markets like Denver, Houston, and Midland often use farm-ins to expand their footprint into new plays-such as the DJ Basin, Permian Basin, Williston Basin, or Powder River Basin-without assuming all exploration costs up front. Farmout agreements also facilitate sharing of geological information, since the farmee’s drilling results give the farmor valuable reservoir data at no direct cost.
Illustrative scenario: Company A holds non-core acreage in a productive but under-capitalized Bakken play. Company B, a well-funded operator on the other side of the basin, farms in by committing to drill two horizontal wells within 18 months. Company A retains a 3% overriding royalty interest and a back-in to 25% working interest after payout, gaining development and geological information without spending money. Company B acquires a meaningful acreage position at a fraction of the cost of buying leases on the open market.
INK™ Law regularly reviews counterparties’ preferred forms for both farm-in and farm out agreements to identify hidden dilution, unfavorable earning requirements, or misaligned operating provisions before clients commit capital.
Key Economic Terms in Farmout Agreements: Overriding Royalty Interest
The economic heart of a farmout lies in how the parties split costs, working interests, and production revenues before and after payout. The economics of a farmout vary based on numerous contractual provisions regarding rights and interests, so precision here is crucial.
Farmouts involve substantial financial investments and long-term operational liabilities. Key economic concepts include:
- Working interest (WI): The percentage of ownership in the lease, responsible for costs and entitled to production net revenues.
- Net revenue interest (NRI): The working interest minus all royalty burdens-including the landowner royalty, any overriding royalty interest, and non-consent penalties.
- Overriding royalty interest (ORRI): A royalty carved from the working interest that is free of production costs. The farmor retains an overriding royalty interest in production as a form of ongoing consideration.
- Carried interest: The farmee may carry the farmor’s share of certain expenses-such as drilling and completion costs-for initial wells or up to a dollar cap.
- Back-in after payout (BIAPO): The farmor reserves the right to convert an ORRI into a working interest once the farmee recovers 100% of its drilling and completion costs.
Example structure: Farmee earns 75% WI before payout (BPO). Farmor retains 25% BPO and a 5% ORRI. After the farmee has recovered all drilling and completion expenses, the farmor backs in to 40% WI after payout (APO). The farmor’s ORRI terminates upon conversion.
These economic terms must be reconciled with provisions in the joint operating agreement, any area of mutual interest (AMI), and existing financing or lien arrangements. Critical provisions in farmouts include earning definitions and payout calculations-getting these wrong can mean the difference between a high return and a costly dispute.
INK™ Law’s corporate and energy finance teams help model project economics, review title and revenue decks, and ensure the farmout supports future capital raises, reserve-based loans, or asset divestitures.
Drilling Obligations: Option Farmouts vs. Obligation Farmouts
An option farmout gives the farmee the right-but not the duty-to drill. If the farmee walks away, it loses the opportunity but faces no liability. An obligation farmout requires the farmee to conduct specified operations; failure triggers damages, reversion, or contractual default. A farmout agreement can require precise definitions of drilling obligations and completion standards.
Typical drilling obligations include:
- Spudding a test well by a fixed date
- Drilling to a specified depth or formation (e.g., to the base of the Niobrara or Bakken)
- Evaluating logs and cores
- Completing the well for production in some deals
Operators use continuous drilling obligations and development schedules-such as one well every 120 days in a development block-to hold acreage, satisfy lessor requirements, and justify infrastructure build-out. Clear definitions in agreements prevent future disputes over terms like “spud,” “initial test,” “commercial production,” and what happens upon failure (termination, partial forfeiture, or cash-in-lieu).
Courts have enforced these obligations strictly. In Moncrief v. Louisiana Land and Exploration Co., the Wyoming Supreme Court found that an obligation to continue drilling once commenced was enforceable when the farmout language specified due diligence and good oilfield practice.
INK™ Law advises clients on negotiating realistic timelines tied to regulatory approvals, rig availability, commodity prices, and capital budgets-and can help renegotiate obligations when market conditions change. The farmee must drill wells as a condition of the agreement, and getting the obligation structure right protects both sides.
The Earning Barrier: Drill-to-Earn vs. Produce-to-Earn
The “earning barrier” is the condition the farmee must satisfy to earn its assignment-and it is one of the most heavily negotiated parts of any farmout agreement.
Drill-to-earn: The farmee earns upon drilling to a contract depth and properly testing a specified formation, even if the well is non-commercial. This protects the farmee from losing its investment on a dry hole while still giving the farmor the benefit of completed operations and geological information. Geological requirements should be clearly outlined in the agreement to avoid ambiguity.
Produce-to-earn: The farmee must achieve production in paying quantities-or some specified level of sustained production-before earning. This shifts more technical and commodity-price risk to the farmee and protects the farmor from assigning interests into wells that never pay out.
When each structure fits:
- In a high-risk exploratory play-say, a rank wildcat in the Piceance Basin-a drill-to-earn provision is crucial to the farmee’s strategy because the probability of a dry hole is significant.
- In a lower-risk development project on proven acreage in the Permian Basin, a produce-to-earn provision may favor the farmor by ensuring only productive wells trigger an assignment.
INK™ Law helps clients calibrate earning barriers to their lease obligations, geologic risk, and financing requirements, drafting precise definitions so both parties reach agreement on what constitutes an earning event.
Interest to Be Earned and Acreage to Be Assigned
A farmout specifies both the type of interest to be assigned and the acreage covered. The contract area may include a single drillsite spacing unit, block farmouts, or checkerboard patterns across multiple sections.
Divided interests allow the farmor to assign 100% of its interest in certain tracts or spacing units while retaining other tracts. This approach focuses the farmee’s operations on core acreage and lets the farmor hold undeveloped land separately.
Undivided interests give the farmee a percentage of the farmor’s working interest across a defined area-such as an AMI-often in proportion to costs paid or wells drilled. An undivided interest structure is common in large-scale development programs where economies of scale push parties toward shared ownership across an entire prospect area.
Accurate legal descriptions, survey references, depth limitations, and formation-specific assignments are essential to avoid disputes. For example, a farmout limited to formations below the base of the Niobrara must clearly define the stratigraphic boundary and how horizontal wellbores crossing that boundary are treated.
Lawyers must coordinate with landmen and title professionals in oil and gas transactions. INK™ Law works closely with landmen, GIS teams, and title attorneys to ensure farmout acreage descriptions align with existing leases, unit designations, and regulatory approvals in states like Colorado, Texas, and North Dakota. Mineral and property laws vary significantly by state, making this coordination essential.
Multiple Wells, Continuous Drilling, and Development Programs
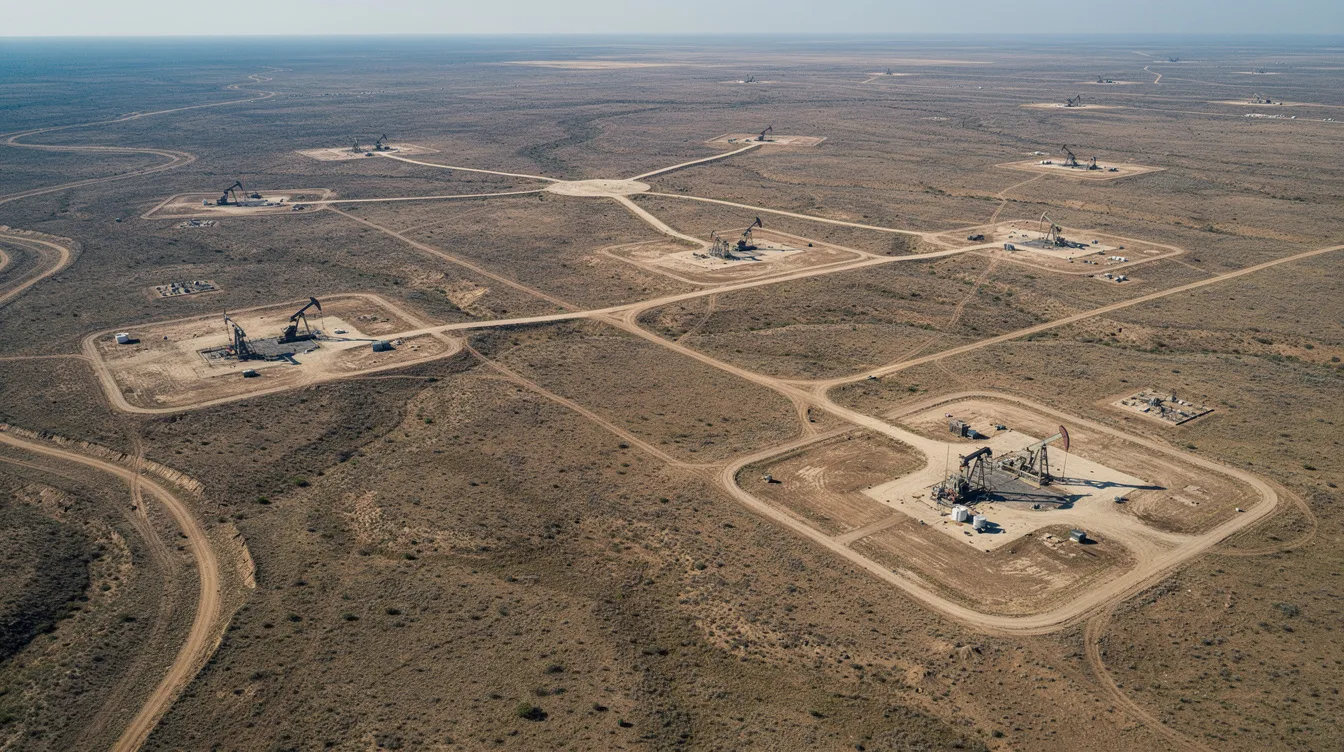
Modern farmout agreements often contemplate multi-well programs rather than a single exploratory test. In shale and tight-oil plays where pad drilling and factory-style development are standard, farmout agreements often include multiple well projects today. A single farmout might cover dozens of wells drilled over several years.
Continuous drilling provisions typically address:
- Required spacing between wells and minimum well counts per year
- Deadlines to commence each subsequent well (e.g., spud well #2 within 180 days of completing well #1)
- What happens if the farmee temporarily pauses drilling for price crashes, rig shortages, or regulatory delays
- Acreage reversion for blocks where the farmee fails to drill additional wells on schedule
Options for additional wells can be structured as granting the farmee the right to drill defined “option wells” in exchange for consistently meeting performance milestones, allowing the farmee to acquire additional acreage as the program expands.
The intersection between continuous drilling obligations in the farmout and similar provisions in underlying oil and gas leases or JOAs is a frequent source of risk. Misalignment can result in unintended forfeiture of leasehold or working interests.
INK™ Law can help design phased development programs and related agreements-including joint operating agreements, midstream dedications, and service contracts-to optimize capital deployment and maintain leasehold across multiple basins. Call (720) 307-2627 to discuss your development program.
Timing of Assignments, Conditions Precedent, and Recording Issues
There are two primary timing structures for farmout assignments. In the first, the farmor makes an immediate assignment subject to reversion if the farmee fails to meet its obligations. In the second, the farmor assigns nothing until the farmee satisfies clearly defined earning conditions-the condition precedent approach.
Common conditions precedent include:
- Regulatory approvals and drilling permits
- Spud dates and depth tests
- Completion operations and well data delivery (logs, cores, pressure tests) within set timeframes
- Execution of JOAs or receipt of consents under existing agreements
Recording assignments-and sometimes memoranda of farmout agreements-in county records protects interests against third parties and secures financing. However, confidentiality concerns may limit how much detail is recorded publicly. Typical issues in farmouts can include third-party consent requirements and tax implications, particularly when JOA consent-to-assign clauses or lease provisions could block or delay the transfer.
Practical drafting should address partial assignments for individual wells, reassignments or terminations for undrilled acreage, and preferential rights or consents to assign under JOAs or leases.
INK™ Law’s energy and real estate teams work together to ensure that farmout assignments, memoranda, and related filings are properly structured, recorded, and integrated with clients’ broader asset strategies.
Negotiating Farmout Agreements: Strategy, Leverage, and Risk Allocation
Farmout negotiations often move quickly and involve dense industry jargon, but the commercial and legal stakes can be substantial-especially for early-stage explorers and PE-backed portfolio companies. Negotiating terms early simplifies the negotiation process and reduces costly renegotiations later.
Key negotiation points:
- Earning barriers (drill-to-earn vs. produce-to-earn)
- Drilling obligations, operatorship, and cost recovery
- Payout definitions and back-in mechanics
- Depth and acreage limitations
- Data sharing and confidentiality
- Environmental and operational liabilities-which must be allocated in farmout agreements
- Default, termination, and cure remedies
Negotiations should consider both parties’ interests and motivations. When the farmor agrees to certain concessions-such as a lower ORRI-it may push for tighter continuous drilling obligations. Conversely, the farmee may trade a portion of its working interest for more flexible development timelines.
Farmout terms must also align with existing credit facilities, hedging arrangements, and investor expectations, especially for companies raising capital through private placements or securities offerings. Farmouts carry complex tax implications including IRS sharing arrangements and IDC deductions that affect after-tax returns for both sides. Understanding the local regulatory frameworks is critical for negotiations involving farmouts. Negotiating operational risk allocations is essential in drafting farmout contracts.
Dispute and litigation insight is important for a transactional lawyer drafting farmout agreements. Practitioners also track evolving farmout issues through resources such as the Gas Law Digest. A good farmout agreement lawyer should provide risk management strategies against defaults and non-performance to keep deals from becoming courtroom battles.
INK™ Law brings together corporate, M&A, energy, and finance capabilities to negotiate farmouts that support future deals-such as asset sales, energy M&A transactions, or joint venture restructurings.
Ready to negotiate a farmout, farm-in, or acreage trade? Call INK™ Law at (720) 307-2627 or send a confidential message for a strategic review of your bargaining position.
Integrating Farmout Agreements with Joint Operating Agreements (JOAs)
In most U.S. oil and gas projects, the JOA governs day-to-day operations, AFEs, non-consent penalties, and decision-making. A farmout agreement is often integrated with Joint Operating Agreements after the farmee earns its interest, so the two documents must be consistent-or at least anticipate one another.
Key coordination points:
- Who will be operator after the farmee earns in
- How non-consent rights interact with earning requirements
- How overhead and COPAS charges are handled
- How new farmees accede to existing JOAs
The JOA and the farmout together determine who controls drilling schedules, completion design, and workovers, which directly affect whether earning barriers are met and when payout occurs.
Potential conflicts arise from JOA consent-to-assign provisions, preferential rights to purchase, and differing definitions of payout or commercially paying quantities. These must be reconciled during drafting to avoid surprises after operations commence.
INK™ Law often reviews or drafts both JOAs and farmout agreements as a package, ensuring consistent definitions and risk allocation so clients are not blindsided by hidden operational or financial constraints.
Farmouts in Modern Energy Portfolios: Shale, Unconventionals, and Carbon-Transition Strategies
Farmout agreements have evolved alongside the rise of shale and unconventional plays, horizontal drilling, and multi-stage hydraulic fracturing in basins like the DJ, Permian, Bakken, and Eagle Ford. What was once a simple, single-well exploration tool is now a sophisticated multi-well development instrument.
Energy companies now use farmouts not only for wildcat exploration but also to allocate capex across core and non-core acreage, monetize non-operated positions, and partner with specialists in particular reservoirs or completion techniques. Business factors like commodity prices, capital availability, and ESG considerations all influence whether a company farms out or farms in to a given prospect.
Emerging uses of farmout-style arrangements extend to carbon transition projects-such as carbon capture and storage (CCS) or integrating renewables into legacy oil and gas fields-where development rights, data sharing, and long-term liabilities must be clearly defined. These transactions involve unique considerations around subsurface storage rights, injection liabilities, and regulatory compliance that differ from traditional upstream farmouts.
INK™ Law’s energy practice spans upstream oil and gas, midstream infrastructure, energy M&A, and renewable energy projects, enabling the firm to structure farmouts that fit broader portfolio and ESG strategies.
Contact INK™ Law at (720) 307-2627 to discuss how farmout agreements can unlock stranded value or support diversification into new energy assets.
How INK™ Law Supports Farmout Transactions and Energy Clients
INK™ Law serves as a strategic legal partner for sophisticated energy and natural resources clients across Colorado, Texas, Wyoming, North Dakota, Oklahoma, Utah, Arizona, and beyond. Upstream oil and gas law involves exploration and production services, and the firm’s energy team handles the full range of transactional work that surrounds these activities.
Farmout-specific services include:
- Drafting and negotiating farmout and farm-in agreements
- Reviewing counterparties’ forms to identify unfavorable terms
- Integrating JOAs and AMIs with farmout structures
- Coordinating with title counsel and landmen
- Structuring related midstream, financing, or M&A transactions
INK™ Law’s broader capabilities-corporate law, mergers and acquisitions, securities, commercial transactions, and outside general counsel-support energy companies through complete deal lifecycles, from initial term sheets to exit events.
A good farmout lawyer should provide risk management strategies against defaults and non-performance, and that is exactly what INK™ Law delivers at every stage of the transaction.
Schedule a confidential consultation by calling (720) 307-2627 or send a message through our secure contact form. Responsive, business-focused advice is available for both new and existing projects.
Our Process for Reviewing and Drafting Farmout Agreements
INK™ Law’s client-centered process emphasizes clarity, speed, and practical recommendations tailored to energy businesses, investors, and operators.
Step-by-step framework:
- Initial consultation: Understand the client’s assets, goals, counterparties, and deal timeline.
- Document and data review: Analyze leases, JOAs, existing farmouts, AFEs, title opinions, and relevant regulatory filings.
- Identify key risks and negotiation priorities: Flag title issues, consent requirements, economic misalignment, and regulatory hurdles.
- Draft or revise agreements: Prepare farmout documents, assignments, memoranda, and supporting instruments.
- Ongoing support: Assist during operations, monitor compliance with earning obligations, and support subsequent transactions.
Clients can expect the firm to coordinate with in-house teams, landmen, and financial advisors throughout the process. Consultations can often be scheduled quickly and handled by phone, video conference, or in-person meetings in Denver, with remote representation for clients operating throughout major U.S. energy markets.
Start the process today by calling INK™ Law at (720) 307-2627 or submitting your project details through the online contact portal for prompt follow-up.
Frequently Asked Questions About Farmout Agreements
When should an operator consider using a farmout agreement instead of selling acreage outright?
Operators often choose farmouts when they want to preserve upside, satisfy leasehold obligations on an oil and gas lease, or obtain technical data-but lack the capital or appetite to drill all prospects themselves. Commodity price volatility, lender constraints, or portfolio rebalancing can make a farmout-rather than an outright sale-the more strategic choice. The farmor gets to retain an overriding royalty interest or back-in rights, keeping skin in the game without fronting the money for leasing operations or drilling.
INK™ Law can help model scenarios comparing a farmout, joint venture, or asset sale to determine which best fits the company’s risk profile and long-term goals.
How do farmout agreements interact with mineral owners and existing oil and gas leases?
A farmout does not change the underlying mineral ownership or lessor relationship. It transfers or shares the working interest subject to existing lease terms. Before entering a farmout, it is essential to confirm lease provisions on drilling requirements, depth severances, continuous development, and consent to assign-and to ensure the farmout does not inadvertently trigger lease termination or breach. Mineral and property laws vary significantly by state, so what works in Texas may not work in Colorado or North Dakota.
INK™ Law reviews key lease clauses and, when necessary, helps clients negotiate consents or amendments with lessors to support the contemplated farmout structure. Visit our mineral rights page for more information.
Can a farmout agreement be used for gas-only or liquids-rich projects, or is it mainly for oil?
Farmout agreements are used across the spectrum of hydrocarbon projects-dry gas, liquids-rich gas, oil, and associated gas-wherever exploration and development risk needs to be shared. In a Haynesville or Piceance Basin natural gas project, for example, the farmout must account for takeaway capacity, gas marketing arrangements, and processing agreements that don’t arise in a pure oil deal. The gas industry relies on these structures just as heavily as the oil side.
INK™ Law has experience with oil and gas and natural gas-focused projects, helping ensure farmout terms align with midstream commitments, processing agreements, and commodity price exposure.
What happens if the farmee fails to drill or meet the earning conditions on time?
The consequences depend on the contract but may include termination of the farmout, reversion of interests, loss of options for additional wells, or agreed liquidated damages. A well-drafted agreement includes clear default and cure provisions-notice requirements, cure periods, and partial forfeiture mechanisms for drilled but non-earning wells or partially developed acreage.
INK™ Law helps clients prevent disputes through precise language. When necessary, the firm works with its commercial litigation team if a farmout disagreement escalates into a formal dispute.
How do I get started with INK™ Law on a new or existing farmout agreement?
Gather your key documents-leases, JOAs, existing amendments, term sheets, and any correspondence with the other party-and schedule a consultation to discuss goals, timelines, and counterparties. The firm is accustomed to tight deal timelines and can often prioritize urgent farmout reviews or negotiations when drilling or lease deadlines are approaching.
Call INK™ Law at (720) 307-2627 or reach out via the online contact form to speak with an energy lawyer about your specific farmout, farm-in, or oil and gas development plans.